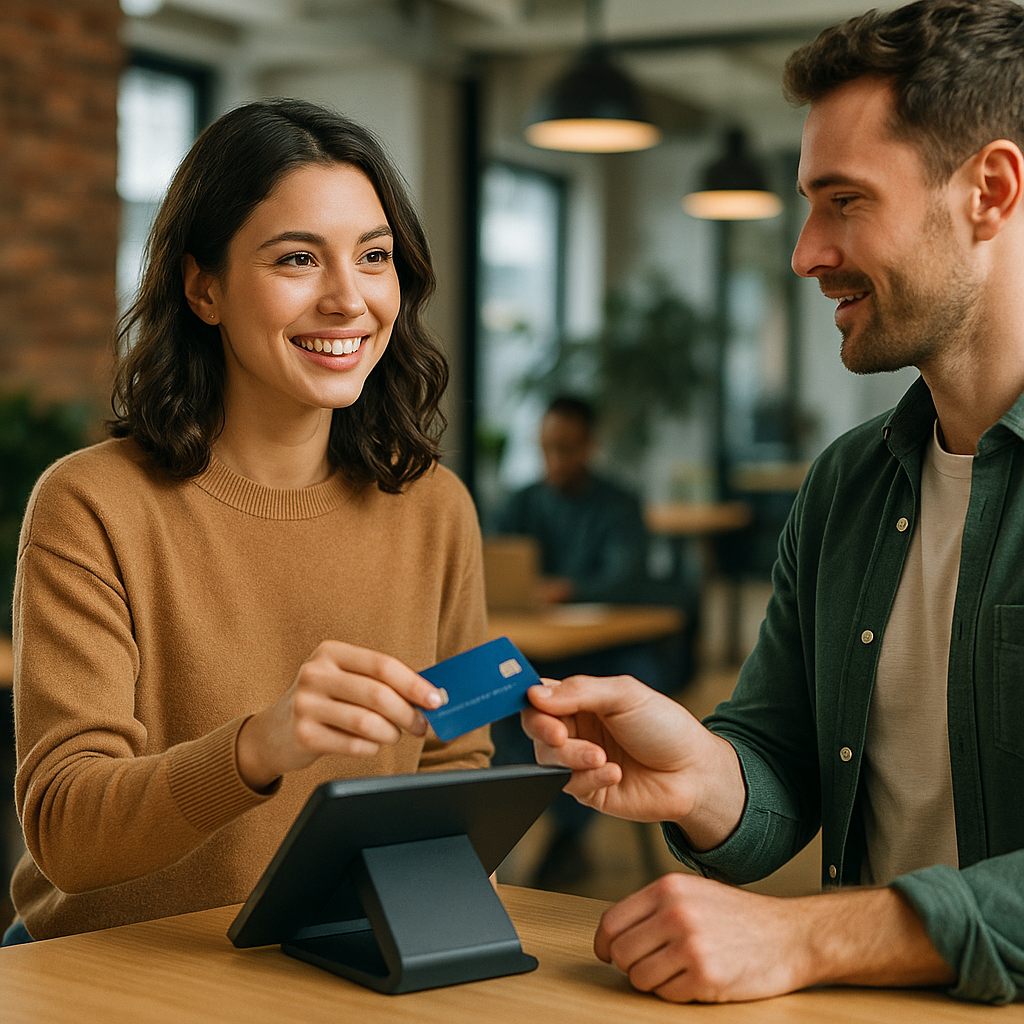
Picture this. A prospect is ready to buy, coffee in hand, credit card at the ready. Then your payment flow hiccups, spins, asks for one more field, and poof. They bounce. That tiny moment just cost you a deal. In 2026, your checkout is your loudest salesperson. Let’s tune it so it sings.
Why Payments Are Suddenly a Board-Level Topic
Payments used to be plumbing. Now they are strategy. For Sales and Commercial leaders, a modern payments stack reduces friction in the buying journey, lifts conversion, and opens new revenue streams. Customers expect to pay however they want, wherever they are, with zero drama. When you deliver that, you earn trust and spend. When you don’t, your competitors will.
1) Modernizing Payments Infrastructure: The Race to Real Time
Legacy gateways and batch settlement slow deals and sour experiences. The leaders are moving to flexible orchestration layers that route across cards, wallets, bank transfers, and local methods, often in real time. The goal is simple: minimize latency, maximize approvals, and make paying feel invisible.
- Offer the right methods. Add the top two local payment methods in every core market before you add the cool experimental one.
- Trim the form. Every extra field is a lost deal waiting to happen. Use address auto-complete and network tokens to keep it fast.
- Route smart. Use an orchestration engine to retry failed transactions via alternate acquirers in milliseconds.
Quick win: benchmark your current authorization rate by market and by payment method. Set a target uplift of 150 to 300 basis points and tie it to quarterly revenue goals. That shifts payments from a cost center into a growth lever.
2) Fraud vs. Friction: Security Without Scaring Off Buyers
Fraud rules that look good on a whiteboard can quietly nuke conversion. The art is calibrating controls so real buyers glide through while bad actors hit a wall. Think adaptive risk rather than one-size-fits-all.
- Tier your checks. Low-risk returning customers should sail through. New, high-ticket, or unusual velocity cases get stepped-up verification.
- Lean on data. Device intelligence, behavioral signals, and network tokens beat blunt AVS declines.
- Pre-negotiate with compliance. Align on acceptable risk thresholds and escalation paths to avoid last-minute vetoes.
Pro tip: report fraud and conversion together. When you only celebrate fewer chargebacks, you might be applauding lost revenue. Your KPI duo is approval rate plus fraud rate, not either on its own.
3) Driving Agility Through Automation: Respond at Market Speed
If your team needs a sprint, a steering committee, and a moon landing to add a new payment method, you are gifting market share to faster rivals. Automation shrinks cycle time, reduces manual errors, and frees sales to sell.
- Automate the boring. Reconciliation, refunds, invoice reminders, and dunning should run without meetings.
- Create reusable playbooks. New market launch equals a pre-baked checklist: methods, pricing, taxes, KYC, anti-fraud, legal sign-offs.
- Instrument everything. Dashboards that surface approval dips or fraud spikes in near real time let you course-correct before the quarter slips.
Consider a payments center of excellence. Give it ownership of tooling, orchestration, and policies with a mandate to enable sales outcomes first, not just reduce costs.
4) Validating Real Business Use Cases: Less Hype, More Revenue
Shiny objects are fun. Budgets are finite. Before you chase the hot new wallet or instant bank rail, pressure-test the use case. You are looking for proof that the change will move a metric that matters.
- Define the outcome. Examples include higher approval rate in Brazil, 20 percent faster settlement for marketplace payouts, or 5 percent lift in subscription renewals.
- Size the prize. Model incremental revenue, cost to implement, and payback period. If it does not clear your hurdle rate, it waits.
- Pilot with purpose. Launch to a small segment, A or B test, and commit to kill or scale decisions based on data, not politics.
Common Pitfalls That Quietly Kill Momentum
- Thinking checkout is an IT project. It is a revenue engine. Sales, Growth, and Finance must co-own it.
- One global setup for every market. Local regulations, 3DS rules, and consumer habits vary. So should your flows.
- Overfitting fraud to last year’s attack. Criminals pivot. Your rules need regular reviews and model refreshes.
- Ignoring failed payment recovery. Smart retries, alternative methods, and friendly reminders save deals at the goal line.
- Letting perfect delay good. A 90-day uplift beats a 12-month rebuild that never ships.
A 90-Day Revenue-First Roadmap
- Days 1 to 15: Baseline approval rates, fraud rates, and latency by market and method. Pick two markets and two methods with the biggest upside.
- Days 16 to 45: Implement quick wins. Add local methods, trim form fields, enable network tokens, and set up smart retries via orchestration.
- Days 46 to 70: Calibrate adaptive fraud with tiered checks. Pre-clear rules with governance. Stand up dashboards for daily monitoring.
- Days 71 to 90: Run a focused pilot. A or B test flows. Document ROI, then take a scale or stop decision with Finance in the room.
What’s Next: The Near-Future of Winning Checkouts
The next 12 to 24 months will bring faster bank-to-bank rails, wider network tokenization, and smarter risk that blends device, behavior, and issuer feedback in real time. Expect embedded payments deeper inside product experiences, more invisible authentication, and more local methods that punch above their weight in conversion. Regulation will keep shifting, so think modular. If each piece of your stack can swap without drama, you will sleep well.
The commercial edge goes to teams that treat payments as a live growth program. Iterate weekly, measure relentlessly, and keep the buyer’s coffee hot by keeping checkout cold and fast.
Your Move
Grab your team for a 30-minute working session. Pull up your approval-rate dashboard, list the top three friction points, and pick one action you can ship in two weeks. Small, measurable wins compound into big revenue. Your loudest salesperson is waiting. Let’s help them close.